
Central Asia is becoming a larger industrial and logistics market. The region faces an estimated $33 billion in annual infrastructure requirements, while trade through the Middle Corridor could potentially triple by 2030. Growth in mining, energy, infrastructure and manufacturing is also creating more demand for heavy, oversized, time-critical and project cargo.
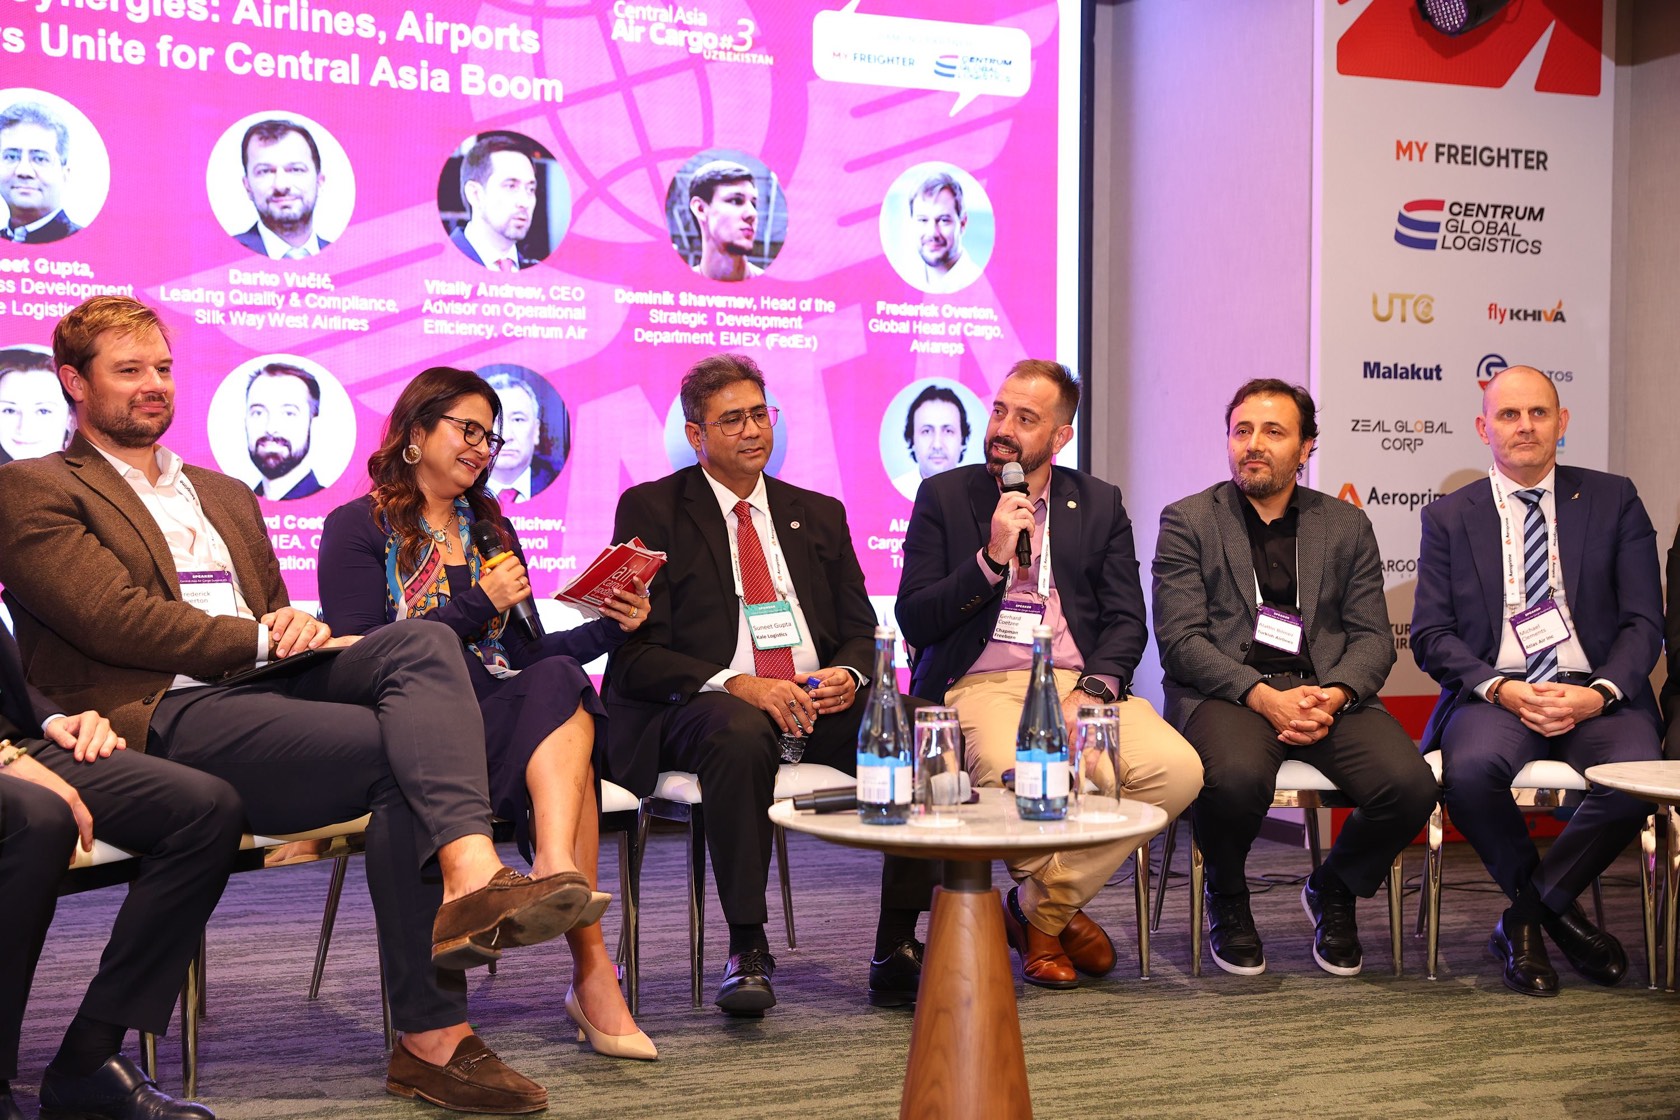
Speaking at the Central Asia Air Cargo Summit, Gerhard Coetzee, Vice President Cargo – IMEA at Chapman Freeborn, said this growth is exposing a gap between the capacity available in the market and the capacity required by the region’s expanding industries.
“The important point is that cargo demand is increasingly being generated inside Central Asia – rather than simply passing through it,” said Coetzee. “Every one of these sectors creates a different type of cargo requirement, and not all of that cargo can move efficiently through a scheduled network.”
When available capacity is not the right capacity
Connectivity between Central Asia and major global markets is improving. China is increasingly connected with Kazakhstan, Uzbekistan and Kyrgyzstan, while scheduled links with Europe are also developing. But more connectivity does not automatically mean suitable capacity for every shipment. The issue is whether the right aircraft is available for the cargo, route and deadline.
This becomes particularly important for project cargo. An aircraft may have sufficient available payload, but the cargo may be too large for the aircraft type, the required route may not be available at the right time, or the airports involved may not have the infrastructure to handle the movement.
For larger aircraft such as the B747F, B777F or AN-124, airport infrastructure and ground handling can determine whether a movement is executable at all. Cargo such as a 70-tonne transformer or 16-metre pipes requires suitable loading equipment, runway capability and specialist handling. Permits and regulatory approvals add another layer, while winter weather and de-icing can affect both timing and operating cost.
“There is an air cargo network, but it isn’t necessarily designed around the cargo that these new industries are generating,” Coetzee said. A scheduled service may work well for standard freight, but a heavy industrial component moving to a remote destination against a project deadline creates a different requirement altogether.
For mining, energy and infrastructure projects, getting that decision wrong can have consequences beyond the shipment itself. A delayed critical component can hold up installation, construction or production, making the cost of downtime significantly more important than the difference between scheduled airfreight and charter.
Matching the aircraft to the cargo
A previous Chapman Freeborn energy project demonstrates the type of planning involved. The company was asked to move urgent manufacturing cargo including 12-metre manifolds requiring purpose-built 12 m × 4 m × 2.4 m transport frames.
The operation was split across two aircraft: a Boeing 767 carried the smaller pieces, while an AN-124 transported the oversized manifolds. Both flights were completed within the required timeframes and the cargo reached the project site.
Although the operation took place outside Central Asia, it illustrates a problem increasingly relevant to the region’s project cargo: the solution has to be built around the cargo rather than simply around available aircraft capacity.
“Aircraft selection isn’t about which aircraft is the biggest. It’s about selecting the most efficient aircraft for the mission,” Coetzee said.
That can mean splitting a movement between aircraft types or using dedicated charter only for the part of a shipment that cannot move through the scheduled network.
From emergency response to capacity planning
Charter therefore complements rather than replaces scheduled airfreight. It becomes relevant when the scheduled network cannot meet a shipment’s weight, dimensions, timing, destination or operational complexity.
The bigger opportunity is to identify those constraints before the cargo is ready to move. For major mining, energy and infrastructure projects, aircraft requirements, airport capability, permits and potential capacity gaps can often be considered during the planning stage rather than once a shipment becomes urgent.
That changes charter from a last-minute response into one of the capacity options available to the project. It also gives shippers more time to assess aircraft, routes and handling requirements before a fixed deadline removes those choices.
As Central Asia becomes more integrated into global supply chains, the challenge will not simply be how much air cargo capacity exists in the region. It will be whether companies can access the right capacity, in the right place and at the point when their project requires it.

