
Investing successfully is not simply about finding an investment that delivers high returns. It is also about deciding how much risk to take, how to protect savings against market uncertainty and how to ensure that investments remain aligned with future financial needs. This is where asset allocation becomes an important part of financial planning.
Whether an individual is investing for retirement, saving for a home or building wealth over time, the distribution of money across different investments can influence the overall performance and stability of a portfolio. A strategy focused entirely on stocks, for instance, may offer considerable growth potential but can expose savings to sharp market declines. Meanwhile, relying exclusively on traditional savings products may provide stability but could limit long-term growth after accounting for inflation.
Asset allocation helps bring these competing priorities into balance. By spreading investments across different asset classes, investors can create a portfolio that reflects their financial goals, investment horizon and capacity to withstand losses.
What Is Asset Allocation? Understanding Its Meaning
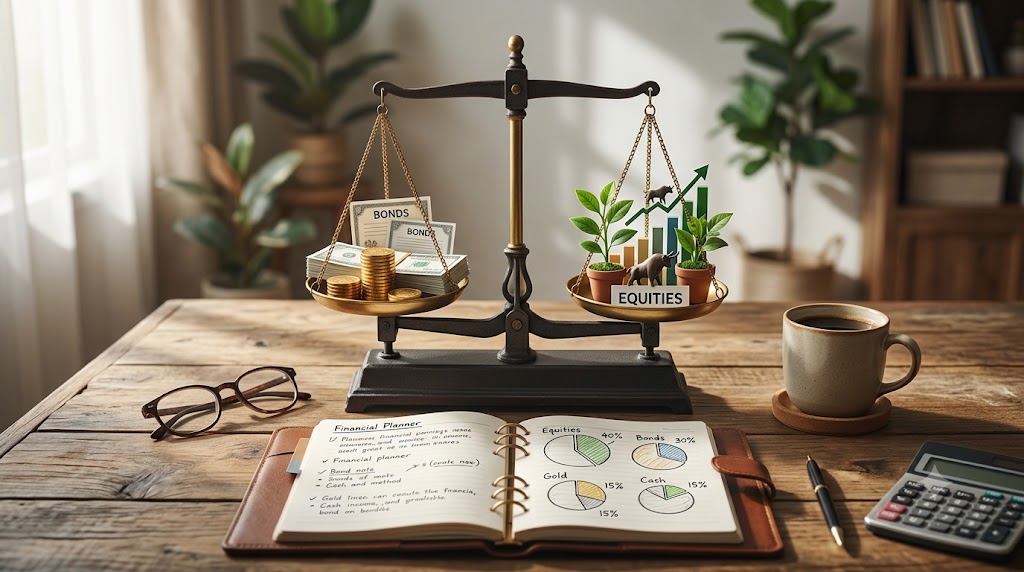
Asset allocation is the process of distributing investments across asset classes such as equities, fixed-income instruments, gold and cash equivalents. Each category has a different role, risk profile and potential return, making the overall combination important to the investor’s financial strategy.
Equities, including stocks and equity mutual funds, can support long-term wealth creation but are subject to market fluctuations. Fixed-income investments, including bonds and certain debt instruments, may offer comparatively predictable income, although they carry risks such as changing interest rates and borrower defaults. Gold can provide diversification during periods of economic uncertainty, while cash and liquid investments help meet short-term expenses.
The appropriate mix depends on individual circumstances. An investor with several decades before retirement may be able to accept greater exposure to equities than someone who expects to use their savings within the next two years.
For example, an investor planning for retirement might combine growth-oriented investments with fixed-income assets and readily accessible savings. The purpose is to avoid depending on a single source of returns while ensuring that money remains available when required.
There is no universal allocation suitable for every investor. The right approach is one that balances growth opportunities with the financial security needed to stay invested through changing market conditions.
Why Asset Allocation Matters More Than Chasing Returns
Financial markets move through periods of growth, uncertainty and decline. An investment that performs well in one economic environment may struggle in another. Asset allocation helps investors prepare for these differences instead of relying on a single investment category to deliver consistent results.
Managing risk without abandoning growth
A portfolio concentrated in equities can experience significant losses during market downturns. Adding other asset classes may reduce dependence on stock market performance, although diversification cannot eliminate investment risk or guarantee positive returns.
The objective is to choose a level of risk that an investor can financially and emotionally manage without jeopardising important goals.
Protecting purchasing power over time
Inflation gradually reduces the amount of goods and services that money can buy. Investments with limited growth potential may struggle to preserve purchasing power over long periods. Growth-oriented assets can help address this challenge, although their returns are uncertain and may fluctuate substantially.
A balanced investment strategy considers both the need for stability and the need for long-term growth.
Keeping financial goals within reach
Different financial goals require different investment approaches. Money intended for a house deposit in the near future may need greater stability and liquidity, while retirement savings accumulated over several decades may allow a longer investment horizon.
Separating investments according to their purpose can help investors avoid taking unnecessary risks with money they will soon need.
Encouraging more disciplined decisions
Market volatility can trigger fear, while a rising market can encourage investors to take excessive risks. A predetermined asset allocation provides a framework for making decisions based on financial objectives rather than short-term emotions.
This discipline can be particularly valuable when markets are unsettled and investors are tempted to make sudden changes to their portfolios.
Understanding the Role of Different Asset Classes
Each asset class contributes differently to an investment portfolio.
Equities for long-term growth: Stocks and equity mutual funds provide exposure to businesses and their potential earnings growth. They can be useful for long-term goals, but investors must be prepared for fluctuations and the possibility of losses.
Fixed income for stability and income: Bonds, fixed deposits and eligible debt investments can provide income and help balance a portfolio’s growth-oriented holdings. Their risks vary according to interest rates, credit quality, maturity and product structure.
Gold for diversification: Gold may behave differently from stocks and bonds under certain economic conditions. Some investors use it as a diversification tool, although its price can also decline and it does not generate regular interest or dividends.
Cash for liquidity: Savings accounts and suitable liquid instruments can help cover emergencies and near-term expenses. While readily accessible money provides flexibility, holding too much in low-return assets over long periods may expose savings to inflation risk.
The aim is not to include every available investment. It is to select a combination in which each asset has a clear purpose.
How to Choose an Appropriate Asset Allocation
A suitable portfolio begins with an honest assessment of personal finances rather than predictions about which market will perform best.
First, identify the financial goal and the date by which the money will be needed. A short investment horizon generally leaves less time to recover from market losses, making capital preservation and liquidity particularly important.
Next, assess risk tolerance and financial capacity. Risk tolerance reflects how comfortably an investor can handle market declines. Financial capacity refers to whether the investor can absorb those losses without affecting essential expenses, debt obligations or future commitments.
Income stability also matters. Someone with irregular earnings may need a larger financial cushion than someone with predictable income and adequate emergency savings.
Age can provide context, but it should not determine investment decisions on its own. A commonly used rule of thumb suggests subtracting one’s age from 100 or 110 to estimate an equity allocation. However, this is only a broad starting point. Financial responsibilities, retirement income, savings and individual risk capacity may justify a different mix.
Asset Allocation Strategies Investors Should Know
Strategic asset allocation involves establishing long-term target proportions for different assets and reviewing the portfolio periodically. This approach emphasises consistency rather than frequent reactions to market movements.
Tactical asset allocation takes a more active approach by temporarily adjusting investments in response to perceived market opportunities. It requires careful judgement and can increase the risk of making costly decisions.
Dynamic asset allocation changes the portfolio according to market indicators, valuations or predefined rules. Certain mutual funds use this approach to adjust their exposure to equities and debt.
Goal-based allocation focuses on the financial objective itself. Instead of maintaining one identical investment mix for every purpose, investors may use different strategies for retirement, education, home ownership and short-term requirements.
For many individuals, a clear long-term plan combined with periodic reviews may be easier to maintain than frequent attempts to predict market movements.
Rebalancing: Maintaining the Intended Level of Risk
An investment portfolio rarely maintains its original proportions automatically. If equities rise faster than other assets, their share of the portfolio increases. The investor may then carry more risk than originally intended.
Rebalancing involves bringing investments back towards their target proportions. This may mean trimming assets that have grown beyond their intended allocation or directing new contributions towards categories that have fallen below their targets.
Investors can review their portfolios at regular intervals or when allocations move beyond predetermined limits. Before making adjustments, they should consider taxes, transaction costs and any changes in their financial goals.
Rebalancing is not a method of predicting market highs and lows. Its purpose is to keep the portfolio aligned with the investor’s chosen risk level.
Common Mistakes That Can Weaken an Investment Plan
One frequent mistake is concentrating too much money in a single asset class because it has recently delivered strong returns. Past performance does not guarantee future results, and market leaders can change.
Other pitfalls include ignoring emergency savings, investing short-term money in highly volatile assets, copying another person’s portfolio and changing allocations whenever financial news creates uncertainty.
Investors may also diversify excessively without understanding how each investment contributes to the portfolio. A simpler, well-structured approach can be easier to monitor and maintain.
Most importantly, an allocation that looks attractive on paper may fail if the investor cannot remain committed during market declines. The strategy must be realistic for both the person’s financial position and emotional comfort with risk.
A Long-Term Approach to Financial Confidence
Asset allocation is not about eliminating uncertainty or finding a perfect formula for investment returns. It is about making deliberate decisions on how money should be distributed to support different financial needs.
By combining suitable growth assets with investments that provide stability and liquidity, individuals can build a portfolio around their priorities rather than short-term market excitement. Regular reviews, sensible rebalancing and disciplined financial planning help keep that strategy relevant as circumstances change.
Ultimately, successful asset allocation begins with understanding what the money is meant to achieve, how much risk the investor can afford to take and when the funds will be needed. A thoughtful investment mix can provide a stronger foundation for pursuing long-term wealth creation while managing the uncertainties that come with investing.

