
by Akash Pharande, Managing Director – Pharande Spaces
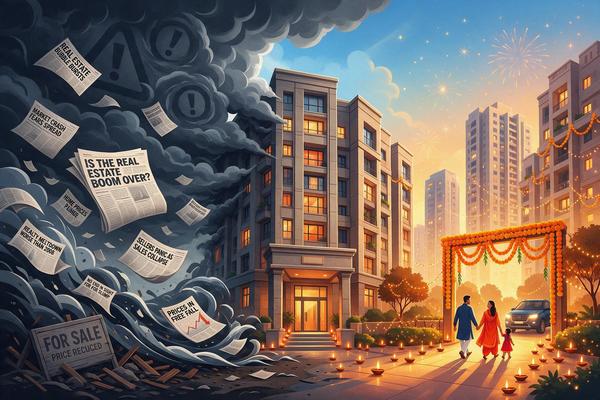
The news is suddenly filled with ‘worry’ pieces – the RBI has raised rates, the West Asia conflict continues to unsettle the economy, and one firm says that housing sales reduced. As developers, we read all of such news – but rest assured, we are still planning for a busy festive season. Why? Because our experience and also the evidence all tell us that such headlines do not sign cheques.
Why the Doomspeak?
It’s obvious why ‘doom and gloom’ stories about the residential property market get so much press. After all, housing touches close to every Indian household, so a story that implies scarcity of any kind – be it on the supply side, the demand side, or both, always have a ready audience. It literally tugs at the Indian heartstrings.
The fact is in real estate, fear-based articles work directly on basic human psychology. A ‘real estate downturn’ angle will always find readers regardless of whether the evidence supports it or not.
The recent rate hike also makes for a tight narrative with a date, a number, a ‘perpetrator’ and a ‘victim’. Nobody ever writes about a quiet strength or recovery in buyer intent, because it lacks sensationalism. You will never find ‘gradual recovery’ in any real estate-related headline.
That’s all fine – reporters have to write such articles to sell papers. The RBI decision does have implications. But when we make an immediate mental leap from rising costs to dwindling demand, developers tend to tune out not because they don’t like the evidence, but because there is no such evidence.
What the Numbers Say
Industry data for July–September 2026 puts housing sales across India’s major cities at roughly 1.02 lakh units. Depending on the tracker and the cities covered, that is anywhere from a 6% fall to a 3% rise over this period in 2025. It broadly averages out at about 1.5% lower. After a year of falling sales, a flat market is not falling but stabilising and as one firm correctly points out, the earlier moderation is cyclical, not structural.
Consider this – according to the data, new launches rose 18% in Q3 2026 and ask yourself – would builders add so much inventory if they expect the market to be declining? A recent survey found that 50% of prospective buyers plan to purchase homes within the next two years. Another 54% believe that macro-economic volatility will at best have a low impact on the Indian housing sector.
Last Year’s Evidence
The best test of the ‘doom’ theory is as recent as last year. Reports said that housing sales in the top cities fell by around 14% in 2025 and attributed it to ‘high prices, IT layoffs and geopolitical tension’. In other words, if there ever was a ‘doom’ year, it would have to be 2025.
However, during the Dussehra–Diwali festive season, most developers saw year-on-year sales shoot up by anywhere between 10–25% in the larger metros – after a sales drop of about 20% across the first nine months of 2025.
Consultancy reports disagreed widely when it came to the last quarter of 2025 – one found sales rising, and another showed a year-on-year drop of 15%. As developers, we do read the news and follow the data, but we also know that such figures are not necessarily the equivalent of the chemistry periodic table. We also follow our instincts, our own sales graphs, and what we know about our customers.
Years When Festivals Did Not Lift Sales
There are notable exceptions, of course. In 2016, demonetisation was announced on 8 November – bang in the middle of the festive quarter – and the market did grind to a halt. In fact, the major cities saw sales drop by anywhere between 35-45% in the October–December quarter (again, the data swings wildly depending on its source). It’s fair to say that housing sales fell by at least 42%, reaching their lowest level since 2010.
Another muted year was 2018., when the October–December quarter saw sales rise by a paltry 4% over the previous quarter thanks to the NBFC crisis. Media stories wrote about a ‘failed festive season’, even though sales still increased – albeit far below the usual festive boost..
In both instances, the market shocks were to money and credit – in 2016, a sudden cash withdrawal and in 2018, a lending squeeze on non-banking financial companies. Buyers found it difficult to pay, and lenders found it harder to lend.
These were not the only standout years for market slowdown, and there are no credible festive-by-festive records related to housing sales. However, even in the pandemic year of 2020, sales rose by well above 70% in the October–December quarter over the previous quarter, from a rather low base.
The point is that such reports completely discount or ignore the human factor, especially the hard-wired Indian drive to homeownership and the festive season spirit that drives housing sales in India. In the above instances, sales fell when homebuyers did not have access to cash or credit. We know that political instability or uncertainty can have a similar effect, though it tends to be more localised rather than nationwide.
Indian homebuyers do not cancel their purchase plans because they read doom-and-gloom reports in the papers.
Real Headwinds
Yes, we are dealing with actual, undeniable headwinds right now. With the RBI increasing the repo rate by 25 bps to 5.50% on 7 October – the first hike since February 2023 – many banks are already lifting their lending rates. On a Rs. 50 lakh loan over a 10-year tenure, this adds about Rs. 66 a month to the EMI, and this can have a real impact on household budgets among budget housing buyers.
The rate hike will cause some stress among affordable and mid-segment buyers, but not on those who are scouting the premium and luxury markets. The RBI’s move is a measured step, but it is not a credit squeeze – lenders continue to lend, banks are open for business, and there is no cash freeze. Most housing loans tend to have tenures of 15-20 years, and rates are bound to fluctuate over such a period. Few buyers set lending rates as perennial red flags. The current headwinds also eventually blow off.
Why Developers Are Calm
Winds, including headwinds, change – but India’s tradition-driven sentiment is not an unpredictable gust of hot or cold air. It is very real. Last year, we saw a ‘gloomy’ 2025 yield a healthy festive uplift. We don’t necessarily expect a bumper Diwali. Homebuyers make purchase decisions based on their current and anticipated employment status, property prices and location, on whether a project incites the necessary spark of decisiveness, and on whether the time is right for the family to take the plunge.
The Indian festive period continues to have a massive cultural relevance and we, as developers, are all geared up to welcome our customers at our sites and confirm bookings during this auspicious period.
About the Author:
Akash Pharande is Managing Dir

