
Investing is not just about choosing the right mutual fund. It is also about deciding how and when to put your money to work. For beginners and experienced investors alike, one common question is whether to invest through a Systematic Investment Plan (SIP) or put a larger amount into the market at once through a lump sum investment.
Both approaches can help investors build wealth over time, but they work differently. A SIP allows individuals to invest a fixed amount at regular intervals, while a lump sum investment involves committing a larger amount upfront. The right choice depends on income stability, available savings, investment goals, risk tolerance and the time available to remain invested.
Rather than treating SIP and lump sum investing as competing strategies, investors should understand how each approach fits into their financial circumstances.
What Is a Systematic Investment Plan (SIP)?
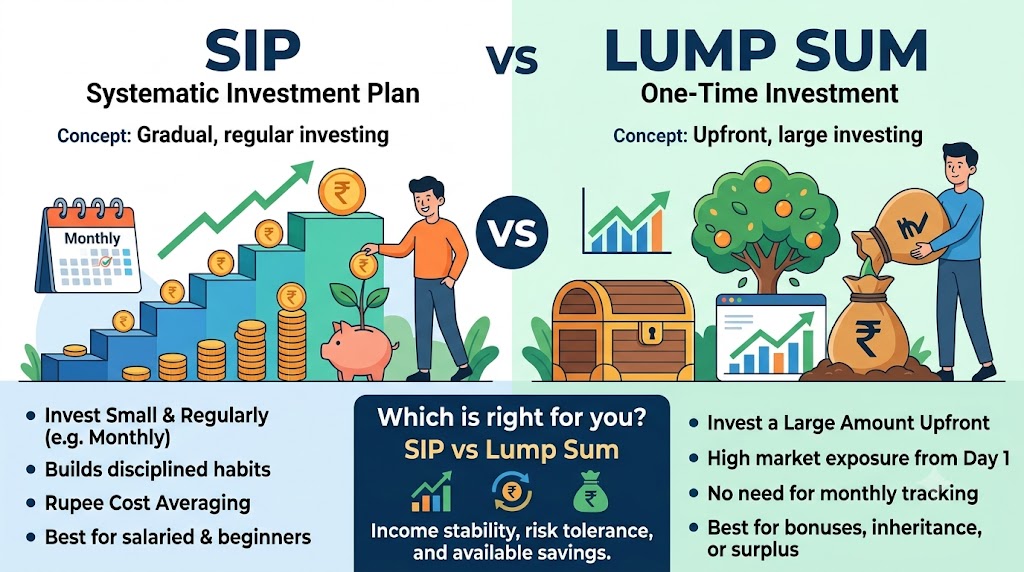
A Systematic Investment Plan is a method of investing a fixed amount in a mutual fund at regular intervals, usually monthly. Instead of waiting until they have accumulated a large sum, investors can begin with smaller contributions and increase them as their income grows.
For salaried professionals, young earners and people building their first investment portfolio, SIPs offer a structured way to invest without putting excessive pressure on monthly finances.
One of the main advantages is rupee cost averaging. When markets fall, a fixed investment amount buys more mutual fund units. When markets rise, the same amount buys fewer units. Over time, this can spread the purchase cost across different market levels.
However, rupee cost averaging does not guarantee profits or protect investors against losses. If the market or the underlying investments perform poorly, a SIP can also deliver negative returns.
How SIPs help investors build wealth
Regular investing can encourage financial discipline by making investing part of a monthly budget. It also allows investors to benefit from compounding, where returns generated over time can contribute to further growth.
Consider an illustrative example of investing ₹5,000 every month for 20 years, assuming a hypothetical annualised return of 12%.
-
Monthly investment: ₹5,000
-
Investment period: 20 years
-
Total amount invested: ₹12 lakh
-
Illustrative investment value: Approximately ₹49.5 lakh
The projected value includes the original contributions and estimated growth. The calculation assumes a constant return for illustration, whereas actual mutual fund returns fluctuate and are not guaranteed. Taxes, expenses and other charges can also affect the final amount.
The important lesson is not the specific figure, but the role of time and consistency. Starting early and continuing to invest through different market cycles can help investors work towards long-term financial goals.
What Is a Lump Sum Investment?
A lump sum investment involves investing a substantial amount of money in a mutual fund at one time. This approach may suit people who receive an annual bonus, inheritance, proceeds from a property sale or accumulated savings that are not required for immediate expenses.
Unlike a SIP, a lump sum investment exposes the entire amount to market movements from the beginning. If markets perform well after the investment, the investor benefits from growth on the full amount. If markets decline, however, the entire investment is affected.
For example, someone with ₹5 lakh available for long-term investment could invest the amount in a suitable mutual fund in one transaction. The eventual outcome would depend on the fund’s performance, market conditions, investment duration and associated costs.
A lump sum strategy can be effective when the investor has sufficient financial reserves, a long investment horizon and the ability to withstand short-term volatility. It does not necessarily require perfect market timing, but investing a large amount just before a market decline can be emotionally and financially challenging.
SIP vs Lump Sum: Understanding the Key Differences
The most important distinction is how the money enters the market. SIPs spread investments over time, while lump sum investing puts the entire amount to work immediately.
| Feature | SIP Investment | Lump Sum Investment |
|---|---|---|
| Investment method | Regular contributions, usually monthly | One-time investment of a larger amount |
| Initial capital | Can begin with relatively small amounts, depending on the fund | Requires a larger amount upfront |
| Market exposure | Builds gradually as contributions are invested | Full amount is exposed from the beginning |
| Cash-flow suitability | Useful for people investing from regular income | Suitable for people with an available surplus |
| Market timing | Reduces the need to choose one entry date | Entry timing can have a greater effect on short-term outcomes |
| Investment discipline | Encourages regular saving and investing | Requires the investor to make a one-time allocation decision |
| Main consideration | Requires continued contributions | Carries immediate exposure to market fluctuations |
Neither method is automatically safer or more profitable. The outcome depends on the investment selected, market performance, timing, costs and holding period.
When Should You Choose a SIP?
A SIP may be suitable when you want to invest gradually while balancing regular expenses and other financial commitments.
You earn a regular income. Monthly contributions can fit naturally into a salary-based budget without requiring a large upfront investment.
You are new to investing. A SIP provides a structured way to begin, although understanding the fund’s risk level and investment objective remains essential.
You have long-term financial goals. Regular investing may help you work towards goals such as retirement, a child’s education or a future home purchase.
You prefer spreading your entry points. Investing at regular intervals reduces dependence on a single market-entry date, though it cannot eliminate market risk.
You want to increase investments over time. A step-up SIP, in which the contribution rises periodically, can help investors increase savings as their earnings improve.
The amount invested should remain realistic. An investor should not commit to a SIP that leaves too little money for household expenses, emergency savings or essential financial obligations.
When Does a Lump Sum Investment Make Sense?
A lump sum investment may be appropriate when an investor has money available beyond immediate needs and a clear plan for deploying it.
You have a substantial surplus. A bonus, inheritance or accumulated savings may provide an opportunity to invest without relying on future monthly contributions.
You have a long investment horizon. Investing earlier gives the money more time to participate in potential market growth, although returns remain uncertain.
You understand your risk tolerance. The ability to remain invested during market declines is important when a large amount is exposed at once.
You have a suitable financial cushion. Emergency savings and near-term expenses should be accounted for before committing a substantial amount to market-linked investments.
Investors do not need to predict the exact market bottom to make a lump sum investment. However, they should be comfortable with the possibility of a decline soon after investing.
Which Strategy Has the Potential to Deliver Higher Returns?
This is where the comparison becomes more nuanced. If the same total amount is available at the beginning and the market rises over the investment period, investing the entire amount earlier may produce higher returns because more money remains invested for longer.
On the other hand, if markets fall soon after the initial investment, a SIP spread across subsequent months may benefit from purchasing units at lower prices. Its relative performance will depend on how the market moves during the investment period.
The comparison also depends on whether investors have the full amount available from day one. Someone investing ₹10,000 from a monthly salary is in a different position from someone who already has ₹5 lakh sitting in a bank account.
For a fair comparison, investors should consider the same total investment amount, the same overall period and realistic cash-flow assumptions.
There is no universal rule that SIPs always generate better returns or that lump sum investments are always more rewarding. Both methods can perform differently under different market conditions.
A Practical Approach: Combining SIP and Lump Sum Investing
Investors do not always have to choose one method exclusively. A combination may work well for people with regular income as well as occasional surplus funds.
For example, an investor could continue a monthly SIP from salary while separately allocating a bonus towards long-term investments. Before doing so, the investor should ensure that emergency savings, high-interest debt and near-term financial needs are adequately addressed.
Someone who is uncomfortable investing a large amount at once may consider spreading the allocation over a period. This can make the decision psychologically easier, but it is important to understand that delaying investment leaves some money uninvested and does not guarantee a better result.
The strategy should reflect financial needs rather than short-term market predictions.
Common Mistakes Investors Should Avoid
Choosing between SIP and lump sum investing is only one part of successful financial planning. Investors should also avoid several common mistakes.
-
Chasing recent returns: A fund that performed well last year may not deliver similar results in the future.
-
Ignoring risk: Equity mutual funds can experience significant declines, even when investments are made through SIPs.
-
Investing emergency money: Funds needed for essential expenses or near-term obligations should not be exposed unnecessarily to market volatility.
-
Stopping investments out of panic: Decisions based solely on short-term market movements can undermine a long-term plan.
-
Expecting guaranteed returns: Mutual fund performance is market-linked, and past performance does not assure future results.
-
Overlooking diversification: Spreading money across suitable asset classes and investments can help manage concentration risk, depending on an investor’s goals and circumstances.
Investors should also review fund costs, tax implications, investment objectives and their own capacity to absorb losses before making a decision.
The Bottom Line
SIP and lump sum investing serve different financial needs. SIPs can help individuals build a disciplined investment habit using regular income, while lump sum investments allow people with available surplus capital to invest immediately.
For beginners and salaried professionals, a SIP may be a practical starting point because it fits into a regular budget and reduces the pressure to choose a single entry date. For investors with substantial surplus funds, a lump sum investment may be appropriate if their financial goals, time horizon and risk tolerance support it.
Ultimately, successful investing depends less on choosing a universally superior method and more on selecting suitable investments, maintaining financial discipline and staying aligned with long-term goals. A well-planned strategy that an investor can sustain through changing market conditions is often more valuable than trying to predict the perfect time to invest.
