
Pic Credit: Pexel
India’s growing digital payments ecosystem is creating opportunities that extend far beyond cashless transactions. For street vendors, neighbourhood retailers, independent service providers and home-based entrepreneurs, accepting digital payments can improve customer convenience while creating a more organised record of business activity. For technology companies, banks and service providers, the same shift is opening up a growing market for affordable tools designed around the needs of small enterprises.
A simple QR code can help a roadside seller accept payments without investing in expensive equipment. Over time, digital transaction records can also support better sales tracking, cash-flow management and financial planning. These capabilities are particularly relevant for microenterprises, where limited working capital and narrow profit margins make efficient business operations essential.
The larger commercial opportunity lies in connecting payment acceptance with services that help small businesses operate and grow. From digital bookkeeping and inventory management to merchant credit and regional-language technology, India’s transition towards digital payments is creating room for new products, partnerships and revenue streams. Businesses that understand the practical challenges of small merchants can help turn this shift into a sustainable growth opportunity.
QR-Code Payments Create a Foundation for Merchant Services
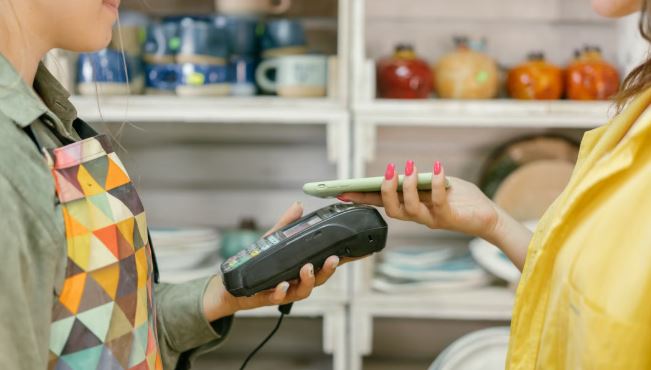
QR-code payments have lowered the barriers to accepting digital money. Small merchants can offer customers a convenient payment option without necessarily investing in traditional card terminals. This makes digital acceptance practical for businesses handling frequent, low-value transactions, including food stalls, vegetable vendors, small grocery shops and local service providers.
For merchants, digital transaction histories can make it easier to review sales and reconcile incoming payments. For service providers, widespread QR-code adoption creates an opportunity to build additional services around the payment process.
Technology companies can develop affordable merchant applications that combine payment notifications with daily sales summaries, digital receipts and basic accounting. Businesses can also offer subscription-based bookkeeping services or tools that help shopkeepers monitor stock and supplier payments.
The commercial potential depends on delivering genuine value. Many small merchants are unlikely to pay for complicated software, but affordable services that save time, reduce errors or improve financial visibility may be more attractive. Providers that keep their products simple and pricing transparent can build stronger merchant relationships and encourage long-term usage.
Voice-Based Technology Creates Opportunities in Local Markets
Digital payment services are evolving to accommodate users who may not be comfortable navigating smartphone applications. Voice-based payment confirmations, audio-enabled devices and regional-language interfaces can make transactions easier to manage during busy trading hours.
This creates opportunities for technology developers, device manufacturers and payment service providers to design solutions for merchants who prefer spoken instructions or need hands-free payment alerts. Affordable devices and simple interfaces may be particularly useful for vendors serving customers throughout the day.
Regional-language support also creates scope for local training, merchant onboarding and customer assistance services. Businesses that help vendors understand payment systems, maintain secure practices and resolve transaction issues can become valuable partners in the wider digital payments ecosystem.
To build a viable market, however, providers must balance accessibility with cost. Devices need to be reliable, notifications accurate and support easy to reach. Products that address these everyday requirements have a stronger foundation for repeat use than those relying solely on novelty.
Digital Payments Can Expand Opportunities in Small-Business Finance
Access to working capital is a major consideration for microenterprises. Merchants often need funds to purchase inventory, replace equipment, prepare for seasonal demand or expand their operations. Businesses with limited financial documentation may find it difficult to demonstrate their income and repayment capacity to formal lenders.
Digital payment records can help provide a clearer view of business activity when considered alongside bank statements, expenses and other relevant information. This creates opportunities for banks and regulated financial institutions to improve merchant assessments and develop financial products suited to eligible small businesses.
Fintech companies can also build services that help merchants organise invoices, monitor cash flow and prepare the information needed for financial assessments. Partnerships between payment providers, banks and merchant-service platforms may make it easier to connect small businesses with appropriate financial products.
However, digital transactions alone do not guarantee credit approval. Responsible lending requires a broader assessment of repayment capacity, existing obligations and loan affordability. For businesses serving this market, transparent terms and suitable repayment structures are essential to building trust and maintaining sustainable customer relationships.
Merchant Data Can Support Smarter Business Decisions
Digital payments can generate useful information about transaction volumes and incoming revenue. When organised appropriately, this information can help merchants understand business patterns and make more informed decisions about purchasing, staffing and stock management.
For example, a retailer who reviews sales records regularly may identify products that sell quickly or periods when demand is stronger. This can help guide inventory purchases and reduce the risk of tying up limited capital in slow-moving stock.
These needs create opportunities for affordable business-management platforms that bring payment records, expense tracking and inventory information together. Providers can serve merchants through simple applications, bundled financial services or partnerships with local business organisations.
Data-driven services must also respect privacy and protect sensitive financial information. Merchants should understand how their data is collected, shared and used. Clear consent, secure systems and transparent practices will be important for maintaining confidence as more business services become digitally connected.
New Opportunities for Banks, Fintech Companies and Local Entrepreneurs
The expansion of digital payments creates several connected business opportunities across India’s small-enterprise economy.
-
Merchant technology: Affordable payment tools, bookkeeping applications, invoicing systems and inventory-management services can help small businesses improve daily operations.
-
Financial services: Banks and regulated lenders can explore suitable accounts, savings products, insurance and working-capital finance for eligible merchants.
-
Merchant onboarding and support: Local service providers can help small businesses set up payment facilities, understand transaction records and learn basic digital-security practices.
-
Regional-language solutions: Developers can create interfaces, training materials and customer-support services designed for merchants who prefer local languages.
-
Business analytics: Simple reporting tools can help merchants interpret sales trends and make better-informed purchasing and cash-flow decisions.
For entrepreneurs entering this market, the opportunity is not simply to attract a large number of merchants. It is to identify a specific problem, provide a practical solution and build a service model that remains affordable for customers with limited resources.
Affordability, Security and Trust Will Determine Market Growth
Despite the opportunities, digital payments providers must account for the realities of small-business operations. Merchants may be reluctant to adopt paid services if they cannot see a clear financial benefit. Network interruptions, failed transactions, fraud risks and complicated complaint procedures can also weaken confidence.
Payment providers need transparent pricing, dependable transaction confirmation and responsive customer support. Merchants should be able to understand applicable charges and settlement conditions without navigating complicated terms.
Security education is equally important. Protecting PINs, verifying incoming payments and recognising fraudulent requests are essential habits for anyone using digital financial services. Providers that invest in practical guidance and accessible dispute resolution can strengthen trust and reduce avoidable problems.
Cash will also continue to serve customers who lack access to digital tools or prefer conventional payment methods. Businesses should therefore focus on giving merchants flexible options rather than assuming every transaction will become cashless.
For companies entering the market, these challenges represent both responsibilities and opportunities. Reliable technology, clear pricing and responsive support can become meaningful points of differentiation in a competitive industry.
The Future of Digital Payments and Small-Business Growth in India
The future of digital payments for street vendors and microenterprises will be shaped by how effectively the ecosystem moves from payment acceptance to broader business support. QR codes have made digital transactions more accessible, but the next commercial opportunity lies in helping merchants manage sales, understand cash flow, access appropriate financial services and make better use of their business records.
For technology providers and financial institutions, this creates scope to develop affordable services that meet the needs of India’s vast base of small enterprises. For merchants, it offers the possibility of more organised operations, improved customer convenience and stronger financial visibility. The greatest value will emerge when these benefits are practical enough to justify their cost and simple enough to fit into everyday trading.
Long-term success will depend on more than transaction growth. Providers must build reliable products, protect merchant information, maintain transparent pricing and offer support that reflects local business conditions. Small enterprises, in turn, need clear information to choose services that match their requirements and financial capacity.
As India’s digital economy continues to develop, digital payments can become an entry point to a wider market for merchant technology and financial services. Businesses that solve real problems for small merchants—rather than simply adding more features—will be better positioned to build lasting relationships and sustainable revenue. The broader opportunity is to make digital finance a practical tool for improving the way India’s smallest businesses operate, compete and grow.

